One of the most common things we hear from new business owners: “I don’t need insurance — I have an LLC.” It is an understandable belief, and it is wrong in a way that costs people real money. An LLC and insurance solve two different problems, and most professionals need both.
What an LLC actually does
A limited liability company separates your personal assets from your business’s obligations. If the business takes on debt it cannot pay, or loses a lawsuit it cannot cover, your house and personal savings are generally shielded — creditors are limited to what the business owns. That separation is valuable, and forming an LLC is usually worth doing.
What an LLC does not do
An LLC does not prevent anyone from suing you, and it does not pay for anything when they do. Three gaps matter most:
- The business’s own assets are fully exposed. Your equipment, business bank account, and receivables are all reachable in a judgment against the LLC. The LLC protects you, not the business.
- Defense costs come out of pocket. Even a meritless claim can cost tens of thousands to defend, and the LLC contributes nothing. Insurance pays defense costs from the first dollar (or after your deductible).
- Personal liability for your own professional acts. In many situations, professionals remain personally liable for their own negligent advice or work — the corporate shield is at its weakest exactly where professional liability insurance is at its strongest.
How the two work together
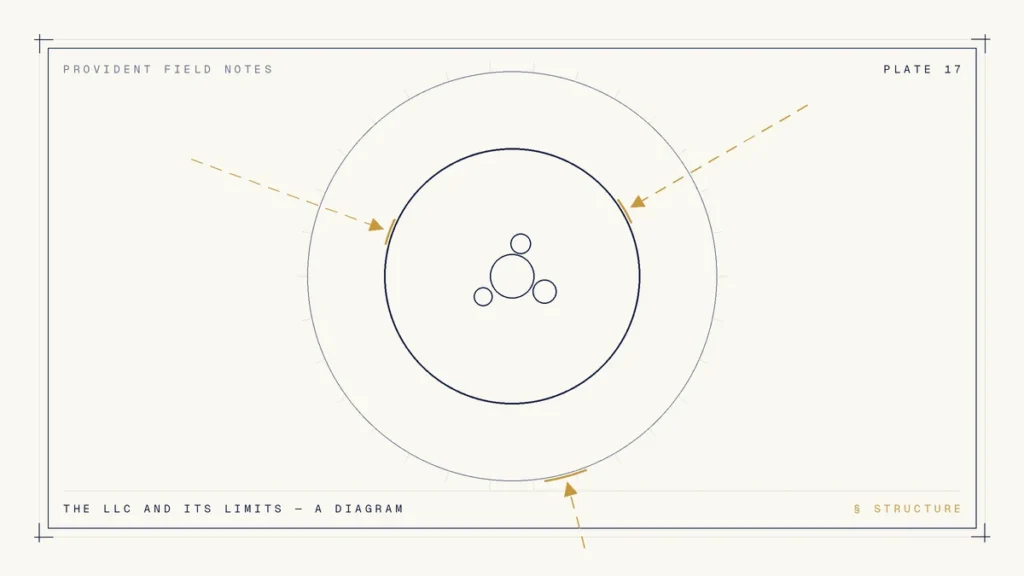
Think of it as layers: the LLC is the structure that keeps a business failure from becoming a personal bankruptcy, and insurance is the funding that keeps a lawsuit from becoming a business failure in the first place. E&O pays to defend and resolve claims about your work; general liability handles bodily injury and property damage; cyber covers data incidents. The LLC catches whatever somehow gets past all of that.
This overview is general information, not legal advice — talk to an attorney about your entity structure.
The practical takeaway
Clients and contracts do not accept an LLC in place of insurance either: certificate requirements ask for proof of coverage, not proof of formation. If your clients require a certificate of insurance, an LLC alone will not get you hired.
See what coverage would cost for your business — quotes from up to 10 A-rated carriers, usually the same day.
Leave a Reply